Showing posts with label Freddie Mac. Show all posts

Thursday, September 18, 2014

Housing Trends from the "Experts"


Experts' View of
Housings Future

In recent posts, housing trends have been a common topic.   Both Housing Activity and Interest Rates are frequently discussed. 

With the "flat" housing market, so many people are on the fence about moving.  By "flat", home sales in number are approximately the same as in 2013.  

Though home values have increased 4-5% in Hampton Roads(around 3% in Virginia and 7% Nationally), the word "flat" has been burned in buyers minds, or it would seem.

Rather, I believe buyers have for the past three years waited during the 1st half of the year to see how the housing market performed.
Watching to see if:

            Home Sales increased
            Mortgage Rates increased or decreased
            Home Values staid firm

As in the past two years, 2014 is shaping up the same way.  The Fall Season will be much stronger than normal.  As in the past two years, this year again the buyers find home sales are steady, rates are still low and home values continue to rise.  

Thus, the buyers react, contact me and are anxious to buy a home or contact their Realtor to write on my listings.  Five homes under contract in the past two weeks!!!

So as you read the experts(courtesy of Albert Clarks' HomeAction Newsletter), you will note the stats and words like "pent up demand".  In reality, they are summarizing that values are increasing, rates are low and the demand for housing is very real and present.

The notes on 2015 will not be a break out year are contingent on those individual that have a need to move having the confidence in jobs and the future of the housing market to make a move.

If all buyers realized how crucial it was to take advantage of the current market trends, these experts will have a different perspective in 2015.

Experts Predict Where US Home Prices Are Headed


Home prices have risen in most U.S. markets this year, with most states reaching price levels not seen since the real estate boom year of 2006. How long will they continue to rise? Check out these predictions from four top housing economists:
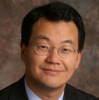
National Association of Realtors Chief Economist Lawrence Yun

"We are in a multiyear housing recovery. For the next five years, we think four of those next five years will be an improving year in terms of home sales given the size of the pent-up demand, provided mortgage rates rise in a modest way."
NAR’s price prediction: Home prices will rise 5 to 6 percent in 2014 and 4 and 5 percent in 2015.
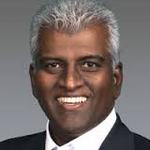
CoreLogic CEO Anand Nallathambi


"Most states are reaching price levels not seen since the boom year of 2006. Our data indicates that this trend will continue, with more states hitting new all-time peaks this year and into 2015 as the recovery continues."
CoreLogic’s price prediction: Prices will rise by 5.7 percent from July 2014 to July 2015.
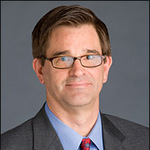
Fannie Mae Chief Economist Doug Duncan

"On the demand side, there appears to be a conservatism among consumers and their willingness to take on big-ticket purchases, such as homes. We currently estimate that 2014 will finish lower in total sales figures than 2013 – and that 2015, while stronger than 2013 and 2014, will not be the breakout year some are expecting."
Fannie Mae’s price prediction: Prices will rise 5.6 percent in 2014 and 4.3 percent in 2015.
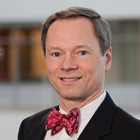
Freddie Mac Chief Economist Frank Nothaft

"House price growth was very strong in 2013 but we don’t expect a repeat performance. Instead, we see housing prices moderate over the next couple of years before settling into its long-run average of about a 1 percent real house price growth per quarter."
Freddie Mac’s price prediction: Prices will rise 5.0 percent in 2014 and 4 percent in 2015.
Wondering what your home is worth in today's market? Contact me and we can discuss it.

Wednesday, April 23, 2014

Mortgage Rates--Latest Projections


Rates Still Forecasted to Rise

  Though presently, as evidenced by the chart below, interest rates struggle to break through the 4.5% level.  Though rates have risen above 4.5% for very short times, rates consistently retreat.

Yet by one very reliable source, Freddie Mac, rates are seen to rise over 1 full percent by the end of 2015.

As seen in the second display, such an increase in interest rate can bedevil a home buyers' effort to attain a home! Over $300 higher house payment due in increasing prices and increasing rates. Higher interest means one's budgeted payment buys less home.  

So acting sooner than later is the best plan!!!


Friday, November 29, 2013

Refinance NOW


Note the picture???

Another heads up on the rising interest rates.  This particular article addressed to home owners looking to refinance their loans.   

Many buyers wishing to buy and home owners wishing to stay and refinance have sat on the sidelines as rates nudged upward.   These buyers and home owners have hoped, maybe even prayed, that the rates would be coming down again.

Yet all signs are the rates will go up.  Some of the signs are:

       Strengthening Economy
       Strengthening Stock Market
       Increasing Demand for Credit
       Increase Pressure for Fed to stop buying mortgage bonds

If you are wise and are a member of these two groups, hears another nail in the coffin of procrastination.


REFINANCE
 RATES WILL RISE IN 2014

Refi Costs Could Rise Next Year

Interest rates and other home loan costs could rise in the year ahead, making it more expensive to refinance your mortgage or purchase a new home in 2014, mortgage market experts say.

Mortgage Bankers Association Chief Economist Jay Brinkmann predicts interest rates will rise above 5 percent in 2014 and to 5.5 percent in 2015.

The monthly payment on a 30-year, $100,000 mortgage is:
  • $477.42 at 4 percent
  • $536.82 at 5 percent
  • $567.79 at 5.5 percent
If rates do rise, homeowners looking to pull cash from their homes may decide it's cheaper to use a home equity loan or line of credit rather thanrefinancing their whole mortgage, Brinkmann said.

Loan Fees Could Go Up
Meanwhile, you could also be paying more for your mortgage next year because mortgage market giants Fannie Mae and Freddie Mac are looking to raise their fees.

Fannie Mae and Freddie Mac loans usually have lower interest rates because the government guarantees the loans. But lenders pay a fee for that guarantee and if Fannie Mae and Freddie Mac raise lender fees, lenders could pass those increases along to homeowners

courtesy of Albert Clark

Tuesday, November 19, 2013

Freddie Mac: Slower Housing Market, Steady Rates Till 2014


As noted previously, in this blog and many other outlets, the rates are expected to go up in 2014.

For those of you looking to buy a home or sell a home, please read this latest confirmation that
the house market slow down coupled with Fed bond purchases will keep rates steady...IN THE SHORT RUN.

The slow down is seasonal and should make a marked improvement in Spring 2014.  All the factors:  low rates, pent up buyer demand, short housing stock(oh this has to change!!) will drive buyers into the market.

So read for the latest but remember acting now is the best time to act.  Waiting will only cost you!!!


Freddie Mac: Slower Housing Market, Steady Rates Till 2014

Tuesday, October 29, 2013

Freddie: Expect a Housing 'Slow Down, Not Shut Down'

Interesting Read!!

It is the first that I have read anywhere about a slow down.  I do expect Hampton Roads to keep
booming.

Perhaps another Government Shutdown in January/February time frame could change everything.  Yet,
I know we all hope that lesson has been learned.


Freddie: Expect a Housing 'Slow Down, Not Shut Down'

Monday, October 7, 2013

Interest Rates: Latest Projections


  With the hubbub now present with the government shutdown, every one has heard about how Fannie Mae, Freddie Mac, USDA Loans etc. are being hindered by the shutdown and lack of staff and lack of funds.

Yet, it is interesting that the rate expectation remain constant for about a year out in 3rd Quarter 2014.
Though the expectations are constant for now.  I wouldn't hold my breath if I were you that this is the final word.   

Besides any impacts of the government shut down of the markets, the improving housing market may increase pressure on interest rates.  So it is no time to wait if you need to move.


Wednesday, September 11, 2013

Interest Rate Projections!

Have your Crystal Ball??

Earlier this week, I shared on the Blog the impact of rising interest rates that occur now or later as the Fed determines here shortly if the $85 Billion buy of bonds and such will be reduced or eliminated.

The impact will be higher rates.   As you can see below, some major players in the mortgage industry have their crystal ball projections as to where rates will be a year from now(3rd qtr 2014).


So what is your projection????  

If I were buying a home right now, I would look at these numbers with a wary eye and act sooner than later.   What if they are off by even 1% in the rate?  It would mean hundreds of dollars to a buyer!


Thursday, August 15, 2013

Policy Update: Mortgage Deduction, Fannie and Freddie could disappear


I know below is a rather long article that I had to put in at it's original size for readability.

Yet as a Realtor, I know that many may not be aware that these topics:  Mortgage Deduction and Closing Fannie and Freddie, are still on the table.

With the coming budget discussions, they could be buried in the "Close down the Gov't" or "Set a budget" showdown coming up.  I would hope our representatives in both houses would be reasonable but present past doesn't give much hope.

Elimination of one or all there of these entities/deductions would directly impact the value of your home or the home you would plan to purchase.

Imagine a world with no deduction for your mortgage insurance and very possible higher mortgage rates.   It will be costly.

So don't let this slide by you as a "government savings".  Since when is something called "savings" when it cost more to do??

Be patient today and read this article

Then ACT!!


Wednesday, August 14, 2013

Mortgage Matters....End of 30 year fixed term Mortgage


Keeping you updated on the market! For the week of 
August 12, 2013

MARKET RECAP
More of the Same, But for How Long?
For now, the cavalcade continues; that is, the cavalcade of home-price increases that began nearly two years ago.
CoreLogic's Home Price Index shows prices increased 1.9% in June compared to May, which marks the 16 th consecutive monthly increase. This latest increase lifts the index's year-over-year gain to 11.9%. For 2013, home prices are already up nearly 10%.
But not all indicators suggest the trend will continue unabated. Trulia's data show asking prices dropped 0.3% in July compared to June, which marks the first monthly decrease since this past November.
A slowdown in home-price gains wouldn't necessarily be bad. We've argued in the recent past, that double-digit yearly price increases are unsustainable. A lower rate of annual increase would be a more sustainable rate, and one more attuned to historical norms. The last thing any of us wants is another bubble market followed by a bubble burst.
We've also a seen a slowdown in the rise in the price of mortgage funding over the past month.
Rates, though higher than they were six months ago, have stabilized. What's more, it appears consumers are becoming acclimated to the new higher-rate reality. A recent survey by Fannie Mae finds that 60% of respondents believe interest rates will increase over the next 12 months. At the same time, three out of four of these respondents believe now is a good time to buy a home. The prospect of buying an appreciating asset appears to trump the higher cost of financing that asset.
But are the respondents expectations properly calibrated?
After the latest employment report, we are less sure of interest rates rising.
The employment report, issued the past Friday, points to sluggish job growth. In July, businesses increased payrolls by only 162,000, roughly 20,000 below most economists' expectations. To be sure, the unemployment rate dropped to 7.4% from 7.6%, but this was attributed to a lower labor-participation rate, which fell to a 35-year low.
The current trend in labor participation runs counter to recent history. After a recession, the labor force usually grows. But this post-recession period has been an anomaly. We are four years into a recovery, yet labor-force growth, as well as job growth, remains stubbornly stagnant.
Many economists believe disappointing job numbers won't dissuade the Federal Reserve from throttling back on quantitative easing. In fact, a few economists speculate the Fed could throttle back as soon as next month. At a minimum, that means mortgages won't drop any further.
We're not convinced, and we don't think most market participants are either. Mortgage rates have held steady for the past six weeks, as has the yield on the benchmark 10-year U.S. Treasury note. Given stubborn economic weakness, we expect quantitative easing to continue through the remainder of 2013.
Moreover, quantitative could even extend deep into 2014, depending on who takes the reigns of the Federal Reserve next year after Chairman Ben Bernanke steps down. Of the frontrunners, one in particular, Janet Yellen, appears keen to keep the Fed's current monetary policies going for a while longer.

Economic
Indicator
Release
Date and Time
Consensus
Estimate
Analysis
Mortgage Applications
Wed., Aug. 14,
7:00 am, ET
None
Important. Purchase activity is picking up as consumers become acclimated to higher lending rates.
Consumer Price Index
(July)
Thurs., Aug. 15,
8:30 am, ET
All Goods: 0.2% (Increase)
Core: 0.2% (Increase)
Important. Consumer-price inflation remains below the Federal Reserve's target rate and will have little impact on interest rates.
Home Builder's Index
(August)
Thurs., Aug. 15,
10:00 am, ET
55 Index
Important. Builders remain confident, but optimism appears to be plateauing.
Housing Starts
(July)
Fri., Aug. 16,
8:30 am, ET
895,000 Units (Annualized)
Important. Starts are expected to return to their upward trajectory after June's disappointing pullback.

The End of the 30-Year Fixed-Rate Loan?
 President Obama caused a stir this week when he said he'd like to see the private sector take over as the primary driver behind the mortgage market. The president went as far as to say he'd like to see Fannie Mae and Freddie Mac dismantled.
It's a worthwhile idea, but there are a few obstacles. For one, the government, through Fannie Mae, Freddie Mac, the FHA, and the Department of Veterans Affairs, backs 90% of all newly originated mortgages. For the most part, there really is no private mortgage market.
At the same time, the president said he'd insist on keeping the 30-year fixed-rate mortgage affordable at today's low rates. Unfortunately, the goal of the prevailing rate on the 30-year fixed-rate mortgage is incongruous with the goal of privatizing the mortgage market. We say that because private money won't lend for 30 years at today's rates without government backing.
So does this mean the end of the 30-year fixed-rate mortgage? That's unlikely. At the same time, it's also unlikely we'll see a mortgage market dominated by the private sector. In other words, it looks like business as usual into the relevant future.